NAIROBI, Kenya – Kenya’s new National Infrastructure Fund has started deploying its 340 billion shilling, about US$2.62 billion, seed capital into domestic government bonds, marking the first public disclosure of how the state-backed investment vehicle plans to finance major infrastructure while drawing private money into the economy.
Founding Chief Executive James Mworia said the fund started buying government securities in July and expects to deploy the full seed capital before the financial year ends in June 2027.
The scale matters. The 340 billion shillings equals roughly one-third of Kenya’s planned domestic borrowing for the current financial year. Such a large institutional investor changes liquidity conditions inside the bond market and gives Nairobi a new financing mechanism beyond direct Treasury development spending.
Mworia said Kenya faces competing fiscal demands.
“We have a high debt service level relative to our income, we have high social needs,” Mworia said.
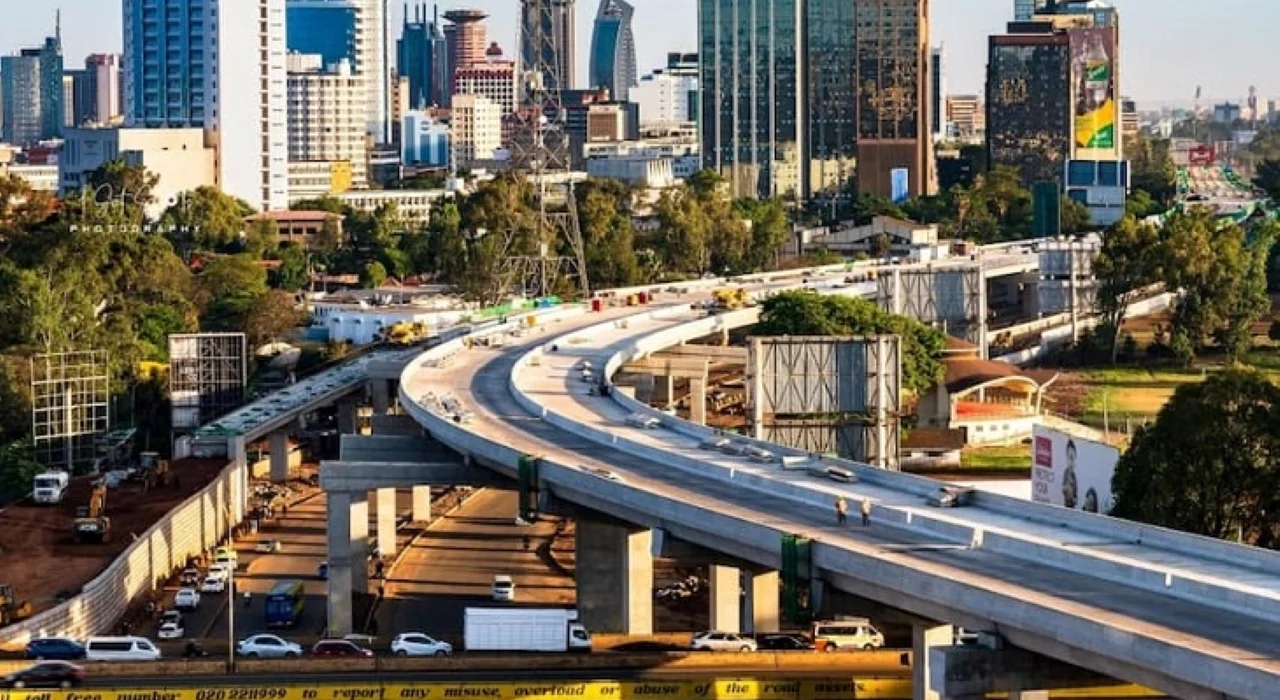
He also pointed toward the country’s infrastructure gap, saying, “But on the other hand, we have an infrastructure deficit.”
Those two pressures define Kenya’s financing problem.
Debt repayments absorb about 40 percent of government revenue. At the same time, roads, energy systems, water networks, digital infrastructure and agricultural facilities require large investment. Higher taxation places pressure on households and businesses, while more public borrowing raises debt servicing costs.
The National Infrastructure Fund seeks another route.
Instead of spending the original capital directly on construction, the fund plans to hold a large bond portfolio, earn investment income and use those returns to support commercially viable projects. Mworia expects the portfolio to generate around 42 billion shillings annually.
The fund targets 3.6 trillion shillings in capital mobilisation over the next decade through co-investment and project-level financing.
Such a model shifts attention from state spending toward investment discipline. Projects need revenue models, cash-flow projections, risk allocation and credible repayment structures. Roads with toll income, power projects with electricity sales, fibre networks with user charges and logistics assets with concession revenue fit more easily into such structures than projects without predictable income.
The fund will focus on energy, transport and logistics, information and communications technology, water and agriculture.
Those sectors directly affect business operating costs.
Poor transport raises freight costs. Power shortages reduce factory output. Weak water infrastructure constrains agriculture and industry. Limited digital connectivity raises transaction costs. Infrastructure investment therefore influences productivity far beyond construction activity.
Mworia expects the bond purchases to release liquidity held by commercial banks.
Kenyan banks rank among the largest holders of domestic government securities. Government debt often offers attractive yields with lower credit risk than loans to private companies. Banks therefore face strong incentives to allocate funds toward Treasury securities instead of businesses.
When the National Infrastructure Fund purchases a larger share of bonds, banks gain room to redirect capital toward companies and households. The policy objective relies on stronger private lending without forcing banks through administrative lending quotas.
Execution will decide whether the strategy delivers that outcome.
Banks still assess credit risk, interest margins and borrower quality. Additional liquidity does not automatically produce productive lending. Businesses need bankable projects, reliable financial records and sufficient cash flow before lenders release credit.
Kenya also needs stable interest rates. High government yields often pull money away from corporate borrowers because banks earn attractive returns from sovereign paper. Lower fiscal pressure and deeper capital markets would strengthen the fund’s broader financing model.
The government created the seed capital through asset sales. Proceeds came from the privatisation of Kenya Pipeline Company and the sale of part of the state’s Safaricom shareholding.
This structure converts state-owned equity into a new investment pool rather than directing privatisation proceeds entirely toward recurrent expenditure.
For investors, governance now becomes central.
A sovereign-backed infrastructure fund needs transparent project selection, independent investment appraisal, procurement discipline and published performance metrics. Poor project choices would weaken returns and place pressure on future public finances. Strong projects would attract pension funds, insurers, banks and foreign institutional investors.
Mworia has previously described the fund’s role as providing development capital, drawing private investment and converting infrastructure opportunities into investable assets. Kenya’s pension industry provides one important source of long-term capital. Retirement funds hold trillions of shillings in assets and seek investments matching long-duration liabilities.
Infrastructure fits this profile when projects generate predictable revenue over long periods.
The fund also plans to invest in the proposed Dangote refinery in Lamu. Mworia confirmed the institution is considering a stake, though officials have not disclosed the investment size.
Such participation would place the fund inside one of Kenya’s largest proposed industrial projects. The refinery plans large-scale petroleum processing on the coast, linking energy security, port logistics, industrial development and regional fuel markets.
The fund is also assessing other projects.
Mworia said domestic and international investors have expressed interest in investing alongside the institution. Co-investment forms a core part of the model because public seed capital alone will not meet Kenya’s infrastructure requirements.
Every shilling of state-backed capital therefore needs to attract additional private money.
Kenya’s approach also deserves attention across Africa. Governments from Ghana to Zambia face similar constraints. Debt servicing consumes large portions of revenue while infrastructure gaps restrict growth. Traditional borrowing becomes harder when interest costs rise or credit ratings weaken.
Infrastructure funds offer one alternative when governments structure them with strong governance and commercial discipline.
Risks remain.
Political pressure might push investment toward weak projects. Cost overruns might destroy expected returns. Currency exposure might affect projects carrying foreign debt. Delayed procurement might stall deployment. Poorly structured public-private partnerships might transfer excessive risk back to taxpayers.
Kenya therefore needs clear separation between political priorities and investment approval.
For Kenyan businesses, the fund’s early bond purchases deserve close attention. More banking liquidity, stronger infrastructure and deeper capital markets would reduce operating constraints across several sectors. Results will depend on whether money moves from securities into productive lending and from investment plans into functioning assets.
The National Infrastructure Fund has now moved beyond policy design into capital deployment.
Kenya’s next test concerns execution. The country has 340 billion shillings in seed capital, a large infrastructure deficit and investors seeking viable projects.
Turning those three elements into roads, power, logistics, water systems and private-sector growth now falls to Mworia and his team.