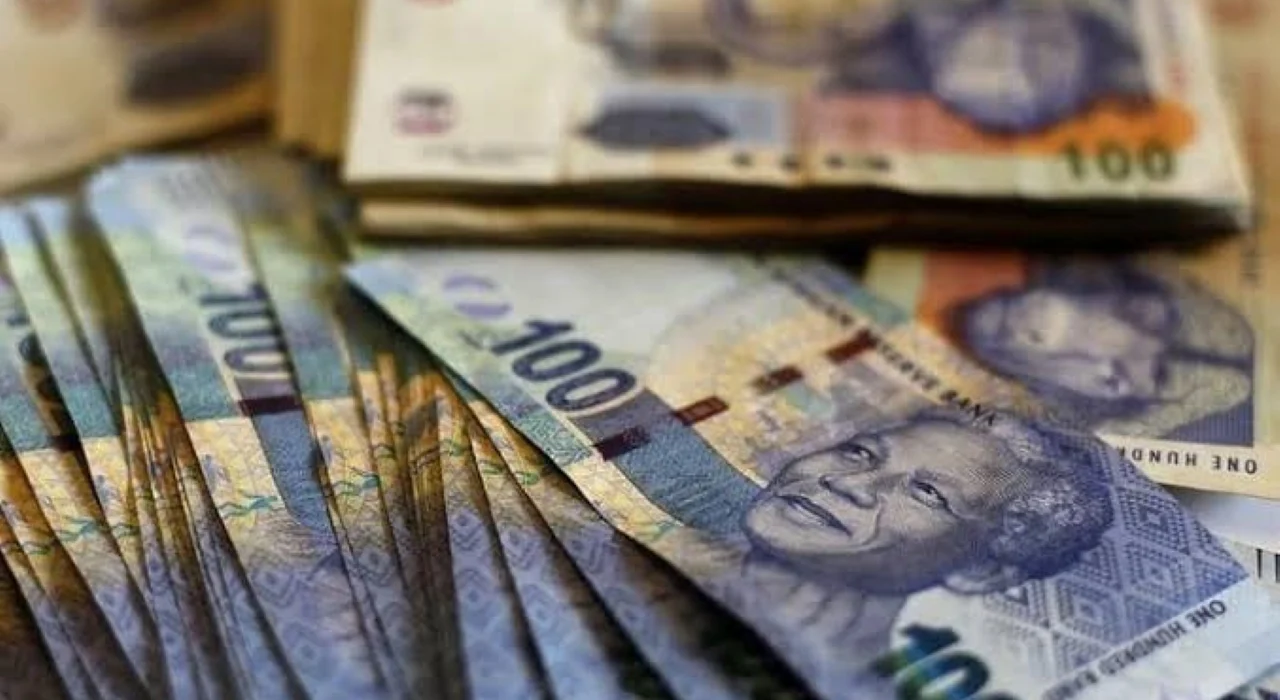
JOHANNESBURG, South Africa – South Africa’s rand headed toward a fourth consecutive weekly loss on Friday as rising United States Treasury yields and renewed dollar demand pulled capital away from emerging markets.
The currency traded near 16.67 against the dollar during morning dealing, after losing about 1.5 percent on Thursday. The weekly decline approached 2 percent, placing the rand on course for its weakest four-week sequence during the current slide.
The move arrived despite stronger domestic indicators. South Africa recorded softer producer inflation, a trade surplus above market forecasts and an improvement in manufacturing sentiment. Those releases would normally support a local currency. Global rates pressure overwhelmed the domestic signals.
Higher United States Treasury yields have changed the pricing of risk across international markets. Investors receive stronger returns from dollar assets, reducing demand for currencies linked to emerging economies. South Africa feels those flows quickly because the rand trades heavily in global foreign exchange markets and often acts as a proxy for broader emerging-market risk.
The pressure extends beyond currency traders. A weaker rand raises the local price of imported fuel, machinery, electronics, industrial inputs and selected food products. Businesses with dollar-denominated costs face tighter margins unless they raise selling prices, hedge currency exposure or secure cheaper suppliers.
Importers therefore face a difficult fourth quarter. Companies carrying thin inventory buffers face stronger replacement costs when new stock arrives. Manufacturers importing components also face higher working-capital requirements.
Exporters receive a different effect. Mining companies, agricultural exporters and manufacturers earning dollars while paying a large share of costs in rand often gain a revenue advantage from currency weakness. Export receipts convert into more local currency, though higher fuel, equipment and finance costs reduce part of the benefit.
South Africa’s domestic data still offered positive signals. The Absa Purchasing Managers’ Index rose to 50.7 points in September from 45.8 in August. A reading above 50 signals expansion. September marked the first return above the neutral level after three consecutive months of contraction.
New sales orders rose sharply to 50.8 from 40.3. Business activity improved to 49.3 from 40.2. The figures suggest factories entered the final quarter with firmer demand after a difficult winter period.
Vehicle sales also showed resilience. Total vehicle sales reached about 61,650 units in September, while year-on-year growth stood near 12.7 percent. Stronger vehicle demand offers support for assembly plants, dealerships, parts suppliers, logistics firms and vehicle finance providers.
The rand failed to respond positively because global capital pricing dominated trading.
United States government bond yields reached levels unseen for more than two decades during the week. Higher yields followed concerns over inflation, oil prices, government debt and expectations around Federal Reserve policy. Investors shifted portfolios toward dollar assets as returns increased.
Paul Mackel, global head of foreign exchange research at HSBC, described the dollar’s position in direct terms. “The dollar is once again looking like the cleanest dirty shirt,” he said.
His assessment captures current market behaviour. Investors still see fiscal and inflation risks inside the United States, yet elevated yields and deep capital markets keep attracting money during periods of global uncertainty.
A fresh United States jobs report later on Friday introduced a new variable. Employers added 29,000 jobs in September, far below expectations near 90,000. Unemployment rose to 4.2 percent from 4.1 percent. Treasury yields eased after the release as traders reduced expectations for another Federal Reserve rate increase in October.
For the rand, lower Treasury yields remove part of the external pressure behind this week’s sell-off. The next foreign exchange sessions will show whether weaker United States labour data changes investor positioning or whether inflation and geopolitical concerns keep the dollar firm.
South African bond markets showed limited relief during early trade. The benchmark 2035 government bond strengthened slightly, with its yield easing by about two basis points to 8.845 percent. The Johannesburg Stock Exchange Top 40 index gained around 0.9 percent during morning trading.
Those moves show investors separating equity valuations, sovereign bonds and foreign exchange risk. A softer currency often supports rand earnings for globally exposed mining and industrial shares, while domestic companies with large import bills face pressure.
Businesses should watch three indicators closely.
First, United States Treasury yields remain a major driver for emerging-market currencies. A sustained move higher raises the return required from riskier assets.
Second, oil prices affect South Africa through the import bill, inflation and transport costs. South Africa imports most of its crude oil and refined fuel requirements. Expensive energy combined with rand weakness places pressure on pump prices and logistics costs.
Third, domestic manufacturing momentum needs follow-through. One PMI reading above 50 gives factories relief, but firms need several months of stronger orders, production and employment before a durable industrial recovery takes shape.
The currency also influences monetary policy. Persistent rand weakness raises imported inflation risk. South African Reserve Bank officials monitor exchange-rate movements alongside food prices, fuel costs, wage growth and inflation expectations. Stronger imported inflation reduces room for lower interest rates.
For households, exchange-rate weakness reaches daily budgets through fuel, transport, imported goods and selected food lines. For businesses, the effect arrives through procurement invoices, hedging costs and debt service.
Companies with foreign-currency exposure should review forward cover, payment schedules and supplier terms. Importers relying on short-term spot purchases face greater volatility than firms with structured hedging policies.
The rand enters the final quarter under pressure from forces outside South Africa, even as domestic manufacturing data improves. The contrast explains Friday’s trading. Better local indicators supported confidence, but global yields controlled capital flows.
South Africa now needs stronger export receipts, sustained factory activity, credible fiscal management and lower global financing pressure to stabilise the currency over a longer horizon.